QBSpecialist

QuickBooks trust account cleanup

QuickBooks trust account cleanup

When the three balances stopped agreeing.

A QuickBooks trust account cleanup brings three balances back into agreement: the trust bank statement, the trust liability on the books, and the sum of every client ledger. Trust activity posted without a client attached, or never recorded at all, is what pulls them apart — and correcting those records is the work.

Last reviewed October 2026 by a Certified QuickBooks ProAdvisor

What this page is based on: the State Bar of California’s Client Trust Account Protection Program (checked October 2026) and our methodology

  • Three balances tied and documented
  • Fixed scope, fixed fee
  • We never move client money

What a QuickBooks trust account cleanup is

A QuickBooks trust account cleanup is the work of finding every trust transaction that was posted without a client attached, attached to the wrong client, or never recorded at all — and correcting the records until the trust bank, the trust liability, and the individual client ledgers all tie to the same figure.

A client trust account holds money that belongs to clients rather than to the firm, so proving it is right means proving two things at once: that the total is correct, and that every client's share of that total is correct. A three-way reconciliation is the check that proves both. When it has not tied for months, the gap does not close by re-running the report — it closes by rebuilding the per-client detail underneath it. That is a cleanup, and it is a different engagement from setting up a firm's books in the first place, which is covered on our QuickBooks for law firms page.

Who needs a trust account cleanup

Firms that reach us usually recognize one of a handful of situations, and all of them share the same underlying symptom: the per-client detail no longer supports the pooled balance.

The most common is a trust account that reconciles against the bank every month but has never been reconciled a third way, so nobody knows whether the client ledgers still sum to the total. Close behind is a file where trust deposits were recorded straight to the trust bank account with no client attached, leaving a liability balance that cannot be broken down by client at all. Others arrive after a bookkeeper leaves, after a merge of two firms' files, or after a migration where trust history came across as one lump. Some arrive because a client asked for a statement of their own funds and the firm could not produce one. Each of those is a records problem with a records fix.

How a trust account cleanup works: attach, rebuild, tie

Trust cleanup, three passes

How a trust account cleanup restores the three-way tie THE ORDER MATTERS PASS 01 Attach Orphans to a client PASS 02 Rebuild Each client ledger PASS 03 Tie All three balances THE RESULT Trust bank = trust liability = sum of client ledgers HELD = OWED
Read this as text

A three-pass flow. Pass one attaches orphaned trust transactions to the client and matter they belong to. Pass two rebuilds each client ledger from that corrected detail. Pass three ties the trust bank, the trust liability and the client-ledger total to the same figure, shown in a confirmed panel reading all three agree. Illustrative, not a real client account.

Illustrative: orphaned transactions are attached to a client first, the per-client ledgers are rebuilt from that corrected detail, and only then can all three balances be tied.

The work runs in three passes, in a fixed order, because each pass depends on the one before it being finished.

The first pass finds trust activity with no client attached and works out who it belongs to, from deposit records, disbursement records, and the firm's own matter files. Nothing is guessed: where the answer is not in the records, that item is listed for the firm to resolve rather than assigned. The second pass rebuilds each client's ledger from the corrected detail, so a statement of one client's funds can be produced on demand. The third pass compares the three balances and works the remaining difference down until they agree — or, where they cannot be made to agree from the records available, documents precisely what is missing and hands it to the firm.

Why a trust account can reconcile and still be wrong

A trust account that reconciles against its bank statement every month can still be wrong, because a bank statement reports one pooled total and knows nothing about which client any dollar belongs to.

The failure has a specific shape. More is disbursed against one client's matter than that client had on deposit. The pooled bank balance still matches the books, because the money did leave the account and the books recorded it leaving. What has happened underneath is that another client's funds covered the difference. Two balances agree; the allocation beneath them does not. A firm can run that way for a long time without noticing, because the monthly reconciliation it performs is the one that cannot see the problem. The third balance — the sum of the individual client ledgers — is what turns an invisible shortfall into a number that does not tie.

Timeline

How long a trust account cleanup takes

A trust cleanup is usually planned at one to two weeks: a view-only review to scope the gap, several days attaching orphaned transactions and rebuilding client ledgers, a pass to tie the three balances, and a handback; your written scope sets the finish date. Files with years of untagged trust activity run longer.

  1. Free review

    Day 0

    View-only look at the trust side of the file; we measure the gap between the three balances and quote a fixed fee.

  2. Attach the orphans

    Days 1–5

    Every trust transaction posted without a client is traced to the client and matter it belongs to, from the records. Anything the records cannot answer is listed, not guessed.

  3. Rebuild the ledgers

    Days 4–8

    Each client's ledger is rebuilt from the corrected detail, so a statement of one client's funds can be produced on demand.

  4. Tie the three balances

    Days 7–10

    Trust bank, trust liability, and the client-ledger total are worked into agreement — or the residual difference is documented precisely.

  5. Hand back

    Day 10

    A tied trust account, per-client ledgers, a written record of every correction, and a written note of how to keep it that way.

Illustrative day numbers. Your written scope sets the schedule.

See how it works

What you get when the trust cleanup is finished

You get a trust account where all three balances tie to the same figure, a per-client ledger you can produce on demand, and a written record of every correction and the reason behind it.

Nothing about the work is a black box. The change record lists each transaction that was moved or attached, which client it went to, and what evidence supported that decision, so the firm — or its accountant, or a reviewer — can audit the reasoning without calling us to explain it. Where the records could not answer a question, that item appears on the list as an open question rather than a quiet assumption. If the operating side of the firm's books also needs work, we scope that separately rather than fold it in.

What changes

A tied trust account vs. one that only reconciles

A tied trust account proves both the total and the allocation; an account that only reconciles against the bank proves the total alone. Here is how the two compare.

A tied trust account vs. one that only reconciles two ways
Tied three waysTwo-way only
Trust bank agrees with the books
Client ledgers sum to the liability
A single client's balance can be produced on demand
A client overdraft would be visible
Every trust transaction carries a client
Corrections documented with their evidence
Firm income untouched by trust activityIt depends
VerdictThe total and the allocation both provenOnly the total proven

What it costs

What a trust account cleanup costs

Every trust cleanup is a fixed scope with a fixed fee, quoted after a free view-only review. The figures below are published starting floors; the review sets the real range for your file.

Trust account cleanup pricing
EngagementStarting pricePlanned timelineWhat's included
Trust account cleanupFrom $1,5001–2 weeksAttach orphaned trust activity, rebuild client ledgers, tie the three balances, one trust account.
Trust + operating cleanupCustom fixed quote2–4 weeksTrust side plus the firm's own operating books in the same engagement.
Multi-account or multi-entityCustom fixed quoteScoped firstMore than one trust account, or trust history carried across from a merge or migration.
Get your range after a free review

Edge cases: unidentified deposits, closed matters, and interest

Four situations decide how a trust cleanup actually runs, and each one has a boundary we hold rather than a judgment we make for you.

Deposits nobody can identify

Trust money whose owner cannot be established from the records is listed as unidentified and handed to the firm — never assigned to a client to make a total balance. Where funds belong, and what happens to money whose owner cannot be found, is a question for the firm and the rules it practices under, not a bookkeeping decision.

Closed matters with a residual balance

A matter that is finished but still shows client funds is flagged with the amount and the date it went quiet. Whether that residual is refunded, applied, or otherwise dealt with is the firm's call; our part is making sure the balance is visible and attributed to the right client rather than buried in a pooled total.

Interest on the trust account

Interest earned on a pooled client trust account is recorded where the firm's arrangement directs, and it is not firm income by default. The handling of that interest is set by the program the account operates under and by the firm's own rules — we record it consistently and document the treatment, and we do not decide it.

Trust activity that ran through the operating account

Client money that passed through the firm's operating account instead of the trust account is documented exactly as found, with dates and amounts, and handed to the firm and its counsel. Correcting the bookkeeping record of what happened is our work; what the firm does about it is not a bookkeeping question and we do not treat it as one.

What QuickBooks does and doesn't do for trust accounting

QuickBooks keeps the trust bank account and the firm's books. It doesn't, by itself, produce the per-client trust ledgers that state bar rules expect, so firms keep those either as sub-customers with a trust liability account per client inside QuickBooks, or in a legal practice-management or trust-accounting application that feeds QuickBooks. Either way, the test is the same three-way reconciliation: the bank statement, the trust account in the books and the total of the client ledgers agree, month by month — set out in our three-way reconciliation reference.

The rules are your state bar's, and they are getting stricter. California is an example: under its Client Trust Account Protection Program, every California lawyer must each year register their IOLTA and non-IOLTA accounts with the State Bar, report each account's December 31 balance, complete a self-assessment of trust-account practices and certify compliance with rule 1.15 — the 2026 reporting deadline was March 30 (State Bar of California, checked October 2026). We reconcile the books to that standard; your bar counsel or ethics hotline answers the rule questions.

How QBSpecialist's trust account cleanup is different

One specialist does the work — the same specialist on the file start to finish — and every correction comes back as a documented change with the evidence that supported it, not a silent adjustment from a rotating pool.

The method is verification rather than assertion. The three balances are captured before anything is touched and re-run after every pass, so the movement can be shown rather than claimed. Access stays minimal: the free review runs on view-only access, and the cleanup uses QuickBooks' accountant access to make and log corrections — never bank logins, and never authority to move money. Above all, we hold a hard line at the edge of bookkeeping. We correct records; we do not move client funds, make disbursements, decide what a client is owed, or take on the firm's compliance obligation.

When not to hire us for a trust account cleanup

Skip us when the trust account already ties three ways, or when the real problem is a legal question rather than a records question.

A firm whose trust bank, trust liability, and client ledgers already agree each period does not need a cleanup — there is no prize for re-doing correct work, and we will say so in the free review. A firm whose trust account is broken because of a dispute over what a client is owed needs its counsel first, not a bookkeeper; we can document what the records show, but we cannot resolve the underlying question and will not pretend to. And a firm that has discovered a genuine shortfall should be talking to its state bar and its counsel about that shortfall before it talks to us about the bookkeeping around it. We will tell you which case you are in during the review, including when the answer is that you do not need us.

What our trust cleanup documents

You do not have to take our word for it. Here is the evidence you can check — the deliverable you receive, the reference behind the method, and our response commitment.

  • Who’s responsible for your file

    A Certified QuickBooks ProAdvisor handles your file from the review through the corrections to the hand-back — the same person throughout, never a rotating pool.

    About QBSpecialist
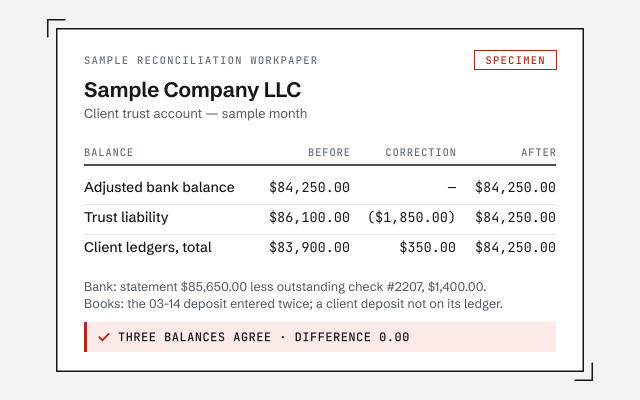
  • Sample reconciliation workpaper — an illustrative trust sheet for Sample Company LLC showing the three balances before and after two documented corrections, in agreement. Marked SPECIMEN, not a real client document. Columns: Balance, Before, Correction, After. Rows: Adjusted bank balance, $84,250.00, —, $84,250.00; Trust liability, $86,100.00, ($1,850.00), $84,250.00; Client ledgers, total, $83,900.00, $350.00, $84,250.00. Bank: statement $85,650.00 less outstanding check #2207, $1,400.00. Books: the 03-14 deposit entered twice; a client deposit not on its ledger. Result: Three balances agree, difference 0.00.Illustrative example — not a client file.

    See a sample reconciliation workpaper

    The single sheet that shows the three balances and the difference worked down between them.

  • The method, in the open

    Three-way reconciliation is the check the whole engagement is built on — read the reference before you hire anyone.

    Read the three-way reconciliation reference
  • Response commitment

    A written reply within one business day.

Remote-first, nationwide

Mon–Sat · 8am–6pm CT

We work entirely remote — view-only access for the free review, QuickBooks' accountant access for the cleanup itself, every change visible to you in the audit log, and every correction recorded in writing. We never hold authority to move client funds.

Questions about trust account cleanup

Why will my trust account not reconcile?

Usually because one of three balances has drifted from the other two: the trust bank statement, the trust liability on the books, and the sum of the individual client ledgers. Which pair disagrees tells you what went wrong — a recording gap between the bank and the books, or a transaction posted to the trust liability without a client attached.

Can a trust account balance while a client is overdrawn?

Yes, and that is exactly why a two-way reconciliation is not enough. The bank reports one pooled total and cannot show how it divides between clients, so the bank and the books can agree perfectly while one client's ledger is short and another client's funds are covering it. Only the per-client total surfaces that.

What does a trust account cleanup actually change?

The records, not the money. We do not move funds between accounts or decide what a client is owed. We find every trust transaction that was posted without a client, attached to the wrong one, or never recorded at all, and correct the bookkeeping so the three balances tie and each client ledger shows what that client actually holds.

Do you handle our trust compliance or reporting to the bar?

No. We do the bookkeeping that your compliance rests on — reconciled balances, per-client ledgers, and a documented trail — but the obligation itself stays with the firm. The reconciliation schedule, the records you must keep, and any reporting or certification to your state bar are the firm's to meet, not ours to assume.

Will you move money or make a disbursement to fix a shortfall?

Never. We do not touch the trust bank account, initiate transfers, or make disbursements. If the cleanup finds that funds are short, we document exactly what we found and hand it to you and your counsel — what to do about a shortfall is a decision for the firm and its bar rules, not a bookkeeping fix.

Does this work in QuickBooks Online or Desktop?

Both. The structure is the same in each — a trust bank account, a matching trust liability account, and every trust transaction tagged to the client and matter it belongs to. Online we work through QuickBooks' accountant access; Desktop by screen-share or a hosted copy of the file. Only the menus differ.

What if we use a dedicated legal trust tool alongside QuickBooks?

That is common and it works. Many firms run a purpose-built legal or practice-management tool for trust and matter balances and bring summarized results into QuickBooks for the general ledger. We clean up and reconcile whichever arrangement you run, and we will tell you plainly where QuickBooks alone is sufficient and where a specialised tool earns its cost.

How long does a trust account cleanup take?

It is usually planned at one to two weeks: a view-only review to scope the gap, several days attaching orphaned transactions to clients and rebuilding the per-client ledgers, a pass to tie all three balances, and a handback; your written scope sets the finish date. Files with years of untagged trust activity, or several matters per client, run longer.

What do we get when the cleanup is finished?

A trust account where the bank, the trust liability, and the sum of the client ledgers all tie to the same figure; a per-client ledger you can produce on demand; a written record of every correction and why it was made; and a written note of how to keep it that way. If the operating side of the file also needs work, we scope that separately.

The trust side rarely arrives alone: the law-firm bookkeeping the account sits inside, the three-way reconciliation that proves it, or the full QuickBooks cleanup this can be part of. The same three legs govern rent held for owners — see QuickBooks for property management.

Not sure how bad it is?

Talk to a QuickBooks specialist.

Describe the file and a specialist will tell you which of these you are dealing with — including when the answer is that you don't need us.

Or start with a free, view-only review