QBSpecialist

QuickBooks for salons and spas

QuickBooks for salons, where the model decides whose revenue it is.

A booth-rental salon and a commission salon look identical from the sidewalk and report nothing alike. Under booth rent, your income is rent and the stylist is a tenant whose tickets never touch your books. Under commission, the whole ticket is yours and the stylist is payroll. Most salons run both at once, and the file has to keep them apart.

One building, two revenue models

How the same client payment lands differently under booth rent and under commission ONE CLIENT PAYMENT $120.00 Service ticket IF THE CHAIR IS RENTED Stylist's income — never enters the salon's books IF THE STYLIST IS ON COMMISSION Salon's service revenue, stylist's share is payroll WHAT THE SALON ACTUALLY EARNED Booth rent, weekly $250.00 Posted as Rental income Both in one sales account REPORTS A BUSINESS ILLUSTRATIVE THAT ISN'T THERE
Read this as text

A client pays 120.00 for a service. Under booth rental, the whole 120.00 is the stylist's income and never enters the salon's books; the salon's revenue is the rent, shown as 250.00 per week, recorded as rental income. Under commission, the full 120.00 is the salon's service revenue and the stylist's share is a payroll expense against it. A confirmed panel notes that pooling both into one sales account reports a business that does not exist. Illustrative figures, not a real salon.

Illustrative: under booth rental the salon's revenue is the rent, not the ticket. The two models cannot share one income line.
  • Rent and service income kept apart
  • Renters tracked as tenants
  • One specialist — never a rotating pool

What QuickBooks for a salon really means

QuickBooks for a salon means building the file around a question most industries never have to ask: when a client pays for a haircut in your building, is that your revenue at all?

The answer depends entirely on how the chair is worked. If the stylist rents that chair, the client's payment is the stylist's income and none of it belongs on your books — your revenue is the rent. If the stylist is on commission, the full ticket is yours and their pay is a payroll expense against it. Same building, same client, same haircut, two completely different sets of books. A salon file that reports strange margins is usually one where that distinction was never built in, and the fix is structural rather than cosmetic. This page is one industry lens on a full QuickBooks cleanup, pointed at a salon's books.

Booth rent is rental income, and the renter is a tenant

Rent collected from a stylist belongs in its own rental income account, kept apart from the service revenue the salon earns on its own chairs, because the two are different kinds of income earned in different ways.

The practical setup follows from that. Each renter is created as a customer, and a recurring invoice matching their lease terms tracks what is owed and what is outstanding — the same way you would track any tenant. Rent that arrives in cash gets a receipt and gets recorded the day it arrives, because a rent ledger that depends on memory stops being a ledger. What a renter does at their chair, what they charge, what product they buy and what they earn is theirs, and none of it belongs in your file. The single most common structural error we find in salon books is a booth renter sitting in payroll, which mislabels a tenant as staff and puts revenue that was never yours into your service income.
Commission stylists are payroll, and the whole ticket is yours

When a stylist works on commission they are an employee, so the full service ticket is the salon's revenue and the stylist's share is a payroll expense recorded against it.

That means withholding, employer taxes, and payroll liability accounts that have to clear each period — the ordinary machinery of employment, none of which exists on the rental side. It also means the product used at the chair is the salon's cost rather than the stylist's, so the true margin on a commission service is the ticket less the commission less the back-bar product consumed. Salons that read only the top line here consistently overestimate what a chair earns, because the cost of delivering the service is spread across three places in the profit and loss. Where the payroll side has already drifted — liabilities that never clear, the same person appearing twice, commission calculated outside the system and pasted in — that is a payroll cleanup rather than something to patch around.

The hybrid salon is the normal case, and where files break

Most salons run both models at once — a few chairs rented, the rest on commission — and the file breaks when a chart of accounts built for one model is asked to report both.

The failure is quiet. Rent and service tickets land in a single "sales" account, so the revenue figure is a blend of two unrelated businesses and the margin on neither can be read. Add a renter who was set up in payroll, or a commission stylist invoiced like a tenant, and the payroll and the receivables both start describing people who are not there. Getting out is not a reporting trick — it is a structural rebuild: rental income and service income as separate lines, renters as customers, commission staff on payroll, and the historical transactions moved to wherever they actually belonged. That is a chart of accounts cleanup with a salon-specific shape, and everything downstream depends on it being done once and done properly.

Retail, back-bar and service are three different costs

Product sold from the shelf, product used at the chair, and the service itself each carry a different cost structure, and a salon file that pools them cannot report margin on any of the three.

Retail product is inventory held for sale: it carries cost of goods sold and, where stock is held, an asset to track and count. Back-bar product — color, developer, the shampoo used during a service — is a supply cost of performing the service; it is consumed, never sold, and it belongs with the cost of delivering the service rather than with retail. Services themselves carry no cost of goods sold at all; their cost is labor. Three streams, three treatments. Pooled into one line, the retail shelf's margin becomes invisible and the true cost of a service is understated by exactly the product it consumed. Where the same item is sometimes sold and sometimes used at the chair, the split follows actual consumption — a policy you set and we then apply consistently rather than re-deciding month to month.

How it starts

How a salon engagement starts

Every engagement opens with a free, view-only review. For a salon, the review asks one question first: does the file know which chairs are rented and which are yours?

  1. Free review

    Day 0

    We read the file view-only and test whether rental income exists as its own line, whether renters are set up as customers, and whether retail and back-bar are separated.

  2. Split the models

    Week 1

    Rental income and service income given separate accounts, renters created as customers with recurring invoices, commission staff confirmed on payroll.

  3. Rebuild the cost side

    Weeks 1–2

    Retail inventory and cost of goods sold separated from back-bar supply cost, and historical transactions moved to where they belonged.

  4. Reconcile and hand back

    Weeks 2–4

    Both revenue streams reconciled to the bank and the payment processor, with a written record of every reclassification.

  5. Keep it monthly

    Ongoing

    Rent invoiced and applied, tickets split by model, and a month-end package that reports rent, service and retail as the three things they are.

Illustrative day numbers. Your written scope sets the schedule.

See how it works

What changes

Salon books built right vs. left generic

A salon file built for the industry can tell you what a rented chair earns and what an owned chair earns. A generic one reports one blended number for two different businesses.

Salon books built right vs. left generic
Built for a salonGeneric setup
Booth rent posted as rental income
Renters set up as customers, not payroll
Rent tracked to each renter and aged
Commission staff run through payrollIt depends
Retail separated from service income
Back-bar cost kept out of retail COGS
Margin readable per revenue stream
VerdictYou know what each chair earnsOne number, two businesses

What it costs

What salon bookkeeping in QuickBooks costs

Every engagement is a fixed scope with a fixed fee, quoted after a free view-only review. The figures below are published starting floors; the review sets the real range for your file.

Salon and spa bookkeeping pricing
EngagementStarting pricePlanned timelineWhat's included
Salon cleanupFrom $1,5002–4 weeksSplit rental from service income, rebuild the renter ledger, separate retail and back-bar cost, one location.
Monthly bookkeepingFrom $400/moOngoingRent invoiced and applied, tickets split by model, month-end package each period.
Multi-locationCustom fixed quoteScoped firstMore than one salon, or a suite-rental operation with many tenants.
Get your range after a free review

Tips, gift cards and the salon software summary

  • Tips. Card tips collected for staff are a liability until paid out through payroll, where they are reported as wages; cash tips reported by staff go through payroll too. The IRS's draft 2026 instructions for Form 8846 extend the employer FICA tip credit to certain beauty service businesses for tax years beginning after 2024 (IRS Form 8846, checked October 2026) — a question for your CPA, but the books have to show tip wages separately for it.
  • Gift cards, packages and memberships are deferred revenue until redeemed or used, not income on the day they are sold.
  • Salon software — SalonBiz, Vagaro, Boulevard and Square are common examples — should post a daily summary: services and retail separately, tax, tips, discounts, refunds and payment types, with processing fees as their own line, so the payout ties.

How QBSpecialist's salon bookkeeping is different

One specialist does the work — the same specialist start to finish — and the two revenue models are separated properly rather than blended into a number that flatters the salon.

The method is verification rather than assertion: rent is reconciled against the renters who actually paid it, so an outstanding balance means someone genuinely owes rent, and service revenue is reconciled to the tickets and the processor rather than assumed from the deposit. Where the records cannot establish which model a historical transaction belonged to, it goes on a list for you rather than being assigned to whichever line makes the totals work. And we hold the boundary at classification: whether a stylist is a tenant, a contractor or an employee is a determination for you with your CPA or employment counsel, and we record it rather than make it. Access stays minimal: view-only for the free review, QuickBooks' accountant access for the work, never your bank or processor logins.

When not to hire us for salon bookkeeping

Skip us when you are a single stylist working alone, or when the real problem is your booking and point-of-sale system rather than your books.

A solo stylist renting one chair has no model-split problem at all — there is one revenue stream, and straightforward bookkeeping or a simple self-employed setup covers it. If what you actually need is a system that books appointments, rings tickets and tracks which stylist did what, that is salon software, and we work alongside it rather than replacing it. And if your file already separates rent from service, tracks renters as customers, and keeps retail apart from back-bar, there is nothing here to buy. The free review will tell you which case you are in, including when the honest answer is that you do not need us.

What our salon engagement documents

You do not have to take our word for it. Here is the evidence you can check — the deliverable you receive, the reference behind the method, and our response commitment.

  • Who’s responsible for your file

    A Certified QuickBooks ProAdvisor handles your file from the review through the corrections to the hand-back — the same person throughout, never a rotating pool.

    About QBSpecialist
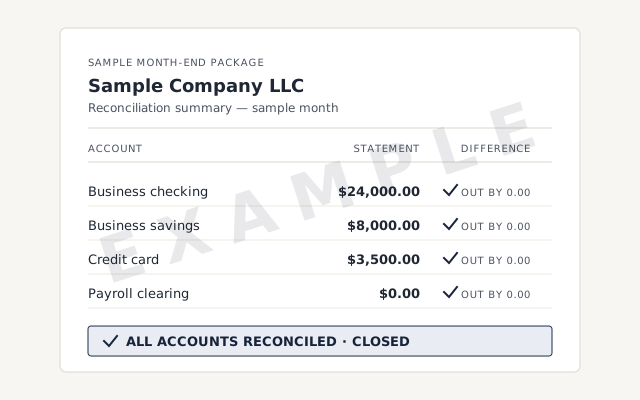
  • Sample month-end package — an illustrative reconciliation summary with every account at a zero difference for Sample Company LLC. Marked SPECIMEN, not a real client document. Columns: Account, Statement, Difference. Rows: Business checking, $24,000.00, ticked, out by 0.00; Business savings, $8,000.00, ticked, out by 0.00; Credit card, $3,500.00, ticked, out by 0.00; Line of credit, $15,000.00, ticked, out by 0.00. Result: All accounts reconciled, closed.Illustrative example — not a client file.

    See a sample month-end package

    The reconciliation summary and revenue-by-stream report a monthly salon client receives.

  • The method, in the open

    Getting the account structure right before anything else is the whole discipline — read how we do it.

    Read the chart of accounts method
  • Response commitment

    A written reply within one business day.

Remote-first, nationwide

Mon–Sat · 8am–6pm CT

We work entirely remote — view-only access for the free review, QuickBooks' accountant access for the work itself, every change visible to you in the audit log, and every reclassified ticket and applied rent payment recorded in writing.

Questions about QuickBooks for salons and spas

Is booth rent service revenue or something else?

It is rental income, and it belongs in its own income account rather than mixed with the service revenue you earn from your own chairs. A booth renter's haircut is not your sale — you did not perform the service and you do not own the ticket. What you earned is rent. Pooling the two produces a revenue figure that describes no business you actually run.

How should a booth renter be set up in QuickBooks?

As a customer, not an employee or a contractor you pay. The relationship runs the other way: the renter owes you money on a lease, so a recurring invoice matching their rental terms tracks what is due and what is outstanding, exactly as it would for any tenant. Setting a renter up in payroll is one of the clearest signs a salon file has the two models confused.

What changes if a stylist is on commission instead?

Nearly everything. A commission stylist is an employee, so the full service ticket is your revenue, their pay runs through payroll with withholding and employer taxes, and the product they use is your cost. A booth renter's ticket never touches your books at all. Two salons with identical chairs and identical foot traffic will report completely different revenue depending on which model they run.

We run both models in one salon — can QuickBooks handle that?

Yes, and it is a common case. The file needs rental income and service income as separate lines, renters set up as customers with recurring invoices, and commission staff on payroll. What breaks a hybrid salon is not the mix itself but a chart of accounts that never acknowledged there was a mix, so both streams land in one 'sales' account and neither can be read.

Should retail product sales be separate from services?

Yes. Retail carries cost of goods sold and, if you hold stock, an inventory asset to track and count. Services carry no COGS — the cost of delivering them is labor, which sits elsewhere. Pooled into one income line, you cannot tell whether the retail shelf earns its space or what a service is genuinely worth after the cost of delivering it.

What about back-bar product — the color and product used during a service?

That is a supply cost of performing the service, not retail inventory held for sale, and it should not sit in the same account as the shampoo on your shelf. Keeping them apart is what makes retail margin readable. Where the same product is sometimes used at the chair and sometimes sold, the split follows how it was actually consumed, which is a policy you set and we record consistently.

Do you decide whether our stylists are renters or employees?

No, and we are firm about that line. Whether a working relationship is a rental, a contractor arrangement or employment depends on the substance of that relationship, and the determination belongs to you with your CPA or employment counsel. What we do is record the classification you have set, consistently, and tell you plainly when the file shows the same person treated two ways.

Do you handle the 1099 and lease paperwork for booth renters?

We keep the books that those filings draw on — what each renter was billed, what they paid, and what is outstanding — but the rental agreements themselves and any reporting obligations attached to them are yours with your CPA. We will not author a filing position for you. What we will do is make sure the underlying record is complete enough to support whatever position you take.

We are behind — can you catch up a salon's books first?

Yes, and the catch-up can come first. Salons fall behind because the ticket volume is high, the payment mix is messy, and rent often arrives as cash or a transfer with no paperwork attached. A catch-up rebuilds the revenue split, applies rent to the renters who paid it, and gets the retail and back-bar cost separated so the margins mean something.

Do you replace our CPA?

No. We keep the books — the revenue split, the rent ledger, the retail and back-bar cost — so the file is accurate and current. Your CPA sets tax positions, advises on classification, and files returns. Good bookkeeping makes that work faster; it does not replace it.

Who the money belongs to is the recurring question: QuickBooks for agencies asks it about pass-through cost, payroll cleanup untangles staff who were set up two ways, chart of accounts cleanup is the structural fix underneath, and all industries lists the rest.

Not sure how bad it is?

Talk to a QuickBooks specialist.

Describe the file and a specialist will tell you which of these you are dealing with — including when the answer is that you don't need us.

Or start with a free, view-only review